|
|
VOL 9 | NUM 4 | 29 September 2026
|
|
|
|
|
|
|
|
IBERIA | 21 - 27 September 2026
|
|
|
|
Power Markets Weekly
is a brief weekly review of the electric market operation in Chile, Mexico, Iberia, France and Italy. If you are not a subscriber, please feel free to subscribe
here
|
|
|
|
|
|
DNV offers tools for Wholesale Market analysis and operation:
- DNV Power Analytics (DNV-PA) is our web-based platform that provides access to constantly updated long-term energy price forecasts.
- With a refined design and an improved user experience we are upgrading our digital services for our customers.
|
|
|
|
|
|
|
Day‑Ahead prices reached a new 2026 weekly average record
|
|
|
|
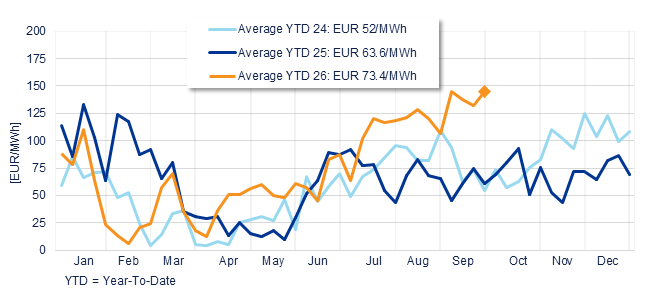
The average price of Day-Ahead Market in Spain reached EUR 144.9/MWh last week, registering a rise of 9.7% compared to the previous week's average (EUR 132.1/MWh). This weekly price was 139% higher than 2025 (EUR 60.6/MWh) and 165% higher than in 2024 (EUR 54.7/MWh).
|
|
YTD average is EUR 73.4/MWh, 15% higher than YTD value in 2025 (EUR 63.6/MWh) and 41% higher than YTD value in 2024 (EUR 52/MWh).
|
|
Annual evolution of the average weekly price of the Spanish Daily Market
|
|
|
|
|
|
|
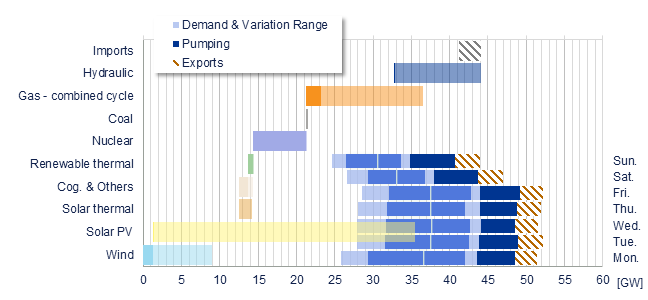
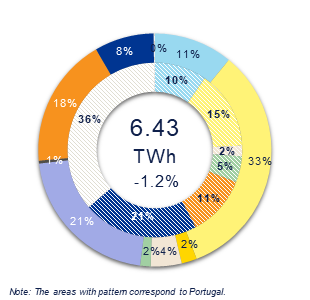
Generation plus imports in Iberia decreased by -1.2%, reaching 6.43 TWh, compared to the 6.51 TWh recorded the previous week.
|
|
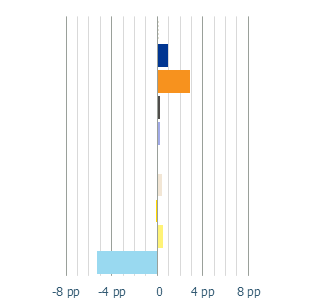
The main changes observed in the energy mix, compared to the previous week, were:
|
- Gas generation increased by 2.9 pp, followed by hydro (1.0 pp)
- Wind generation decreased by 5.3 pp
|
|
Global renewable energy share decreased from 61.2% to 57.2% since the previous week.
|
|
Generation Mix Iberia
|
|
|
|
|
Variation Iberia
|
|
|
|
|
|
Nuclear
|
|
Cogeneration
|
|
Renewable thermal
|
|
Coal
|
|
Combined cycle
|
|
|
Hydraulic
|
|
Wind
|
|
Solar PV
|
|
Solar thermal
|
|
Imports
|
|
|
|
Power range by energy sources vs demand Iberia
|
|
|
|
|
|
|
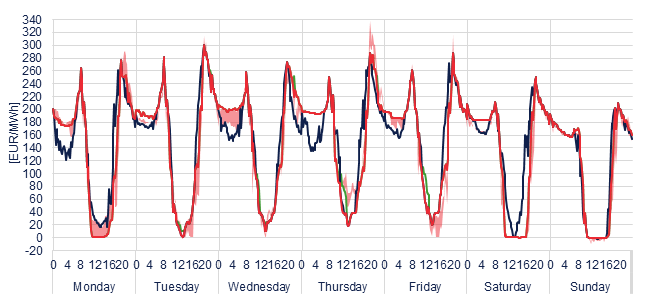
Hourly prices reached their highest weekly average of 2026, as strong morning and evening ramps more than offset the price relief observed during solar hours. While prices still dropped to floor levels on most days, these periods were shorter than in previous weeks, with values above EUR 150/MWh recorded during 63% of the hours. Portuguese prices averaged slightly higher than in Spain, reflecting recurring decoupling during midday hours on several days of the week.
|
|
The weekly maximum was EUR 300/MWh, reached on Tuesday at 7:45 p.m., coupled with Portugal and France. Minimum price, EUR -0.07/MWh was reached on Sunday between 1:00 p.m. and 1:15 p.m.
|
|
The SWE grid coupling was 38%, higher than recorded the previous week, 35%.
|
- Spain-Portugal: 90%
- Spain-France: 43%
- SWE (ES-PT-FR): 38%
|
|
Weekly evolution of the hourly price of the Day-ahead and Intraday Market (DAM and IM)
|
|
|
|
|
|
|
Spanish DAM
EUR 144.9/MWh
|
|
Spanish IM
EUR 142.3/MWh
|
|
Portugal DAM
EUR 146/MWh
|
|
France DAM
EUR 147.7/MWh
|
|
|
|
|
|
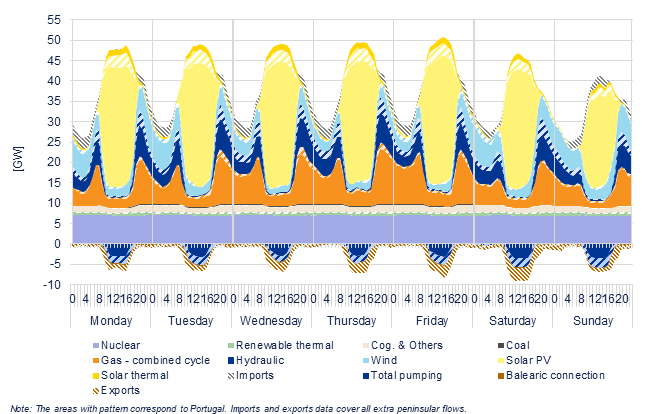
Hourly detail of the generation & interconnections in Iberia
|
|
The highlights from last week
|
- The hourly average output of nuclear generation was 7 GW, with all the nuclear fleet operative
|
- Solar PV was the first source of electricity during 42% of the week, followed by gas (40%) and wind (8%)
- Hourly renewable share fluctuated between 28% and 77% of total generation, compared to the previous week, 28% and 78%. Wind's maximum share reached 29% of hourly generation, while solar PV's maximum share reached 68%
|
|
Solar and wind generation
|
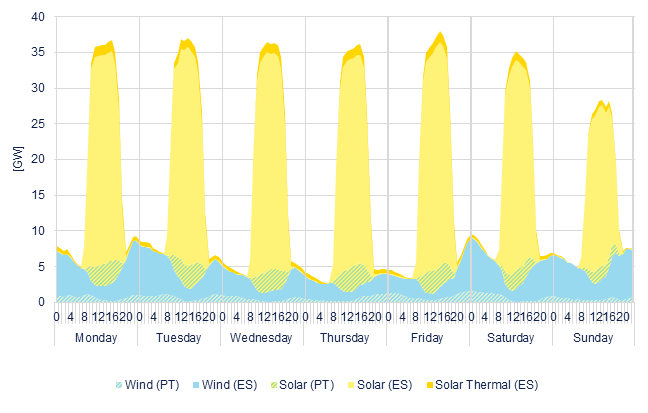
- Wind generation was 0.7 TWh, 33% lower than the previous week.
- Solar PV generation was 2 TWh, 0.2% higher than the previous week.
|
|
Generation by technology Iberia
|
|
|
|
|
|
|
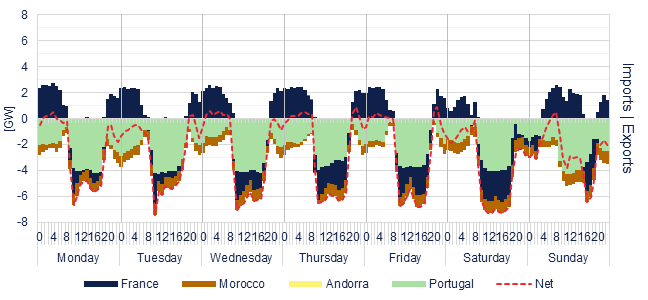
Interconnections by country, from Spain
|
|
|
|
|
|
|
Hourly wind & solar generation
|
|
|
|
|
|
Solar PV Captured Price
|
Wind Captured Price
|
|
|
|
|
|
Spain
EUR 60/MWh
|
|
Portugal
EUR 58.3/MWh
|
|
|
|
Spain
EUR 165.8/MWh
|
|
Portugal
EUR 172.6/MWh
|
|
|
|
|
|
*The solar / wind price has been calculated as the DA price weighted by the solar / wind generation of the peninsula.
|
|
|
|
|
Futures Market & Commodities
|
|
On the oil market, prices remained volatile as renewed diplomatic efforts between the US and Iran failed to deliver a breakthrough. While talks at the UN General Assembly initially raised hopes of reopening the Strait of Hormuz, negotiations produced little tangible progress and uncertainty over regional oil flows persisted. Prices briefly fell below USD 100/bbl early in the week, but later rebounded as traders reassessed the prospects for a quick resolution and continued to price in ongoing supply risks. Overall, settlements increased from USD 100.34/bbl (Monday) to USD 104.32/bbl (Friday), within a range of USD 97.36–108.23/bbl.
|
|
European gas prices fell to their lowest level in three weeks as markets unwound part of the geopolitical risk premium built up earlier this month. However, fundamentals remained supportive. Ongoing outages at Norway’s Troll field and low storage levels continued to fuel concerns over winter supply adequacy, with EU inventories reaching 70.4% of capacity, compared to 82.0% a year ago. Overall, settlements fell from EUR 73.25/MWh (Monday) to EUR 72.07/MWh (Friday), within a range of EUR 68.65–80.55/MWh.
|
|
European carbon prices traded within the EUR 85–88/t range despite ongoing volatility across energy markets. Compliance buying ahead of the 30 September deadline continued to provide support, while rising gas and oil prices helped keep EUAs close to recent highs. Gains were capped by uncertainty surrounding the EU ETS reform discussions and an increase in speculative short positions, which reached their highest level since April. As a result, the market remained range‑bound despite strong underlying energy fundamentals. Overall, settlements increased from EUR 86.59/t (Monday) to EUR 86.78/t (Friday), within a range of EUR 85.38–87.75/t.
|
|
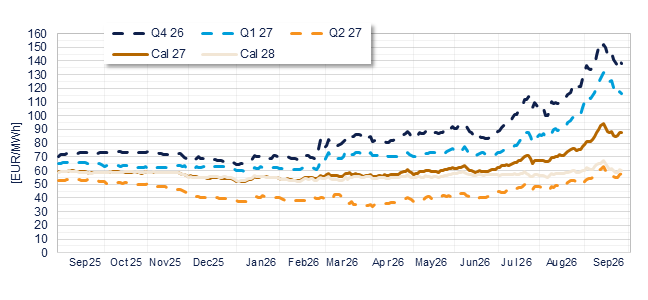
Finally, power futures dropped. Q4 26 closed decreasing 5.7% at EUR 138/MWh, while Q1 27 decreased by 7.5% to EUR 116.5/MWh. Q2 27 rose by 2.3% to EUR 58/MWh. For annual contracts, Cal 27 decreased by 0.8% to EUR 87.8/MWh, and Cal 28 decreased by 2.8% to EUR 60/MWh.
|
Why you are receiving this email
|
You are receiving this email because you are subscribed to our Power Markets Weekly report - IBERIA. If you no longer wish to receive this report, or if you would like to subscribe to other regional reports, you can manage your subscription using the button on the right.
|
|
|
|
DNV, Calle Santa Maria Magdalena 14, 28016 Madrid
|
|
|
|
|
This e-mail and any attachments thereto may contain confidential information and/or information protected by intellectual property rights for the exclusive attention of the intended addressees named above. If you have received this transmission in error, please immediately notify the sender by return e-mail and delete this message and its attachments. Unauthorized use, copying or further full or partial distribution of this e-mail or its contents is prohibited.
|
Your
data appears in a file under the responsibility of DNV Maritime and Energy, S.L.U. - NIF: 82800798 Postal address: Calle Santa Maria Magdalena, 14 - Planta 2, 28016, Madrid, E-mail: power-markets-weekly@dnv.com. On behalf of the company we treat the information you provide us with in order to send you market information, information related to our services and invitations to events. The data provided will be kept as long as you do not request the cessation of the activity. The data will not be transferred to third parties except in cases where there is a legal obligation. You have the right to obtain confirmation on whether in DNV GL Services Spain S.L. we are treating your personal data so you have the right to access your personal data, rectify inaccurate data or request its deletion when the data is no longer necessary.
|
DNV GL Services Spain S.L. publishes this weekly report using public information from OMIE, REE y MEFF. This document is for information purposes only. Its partial or total reproduction is authorized while mentioning its source as DNV. Opinions herein expressed are proprietary.
|
|
|