|
|
VOL 13 | NUM 10 | 25 September 2026
|
|
|
|
|
|
|
|
CHILE | 14 - 20 September 2026
|
|
|
|
Power Markets Weekly
is a brief weekly review of the electric market operation in Chile, Mexico, Iberia, France and Italy. If you are not a subscriber, please feel free to subscribe
here
|
|
|
|
|
|
DNV offers tools for Wholesale Market analysis and operation:
- DNV Power Analytics (DNV-PA) is our web-based platform that provides access to constantly updated long-term energy price forecasts.
- With a refined design and an improved user experience we are upgrading our digital services for our customers.
|
|
|
|
|
|
|
No 'Fiestas Patrias' break for the Ancoa – Charrúa congestion as it persisted during the holidays
|
|
|
|
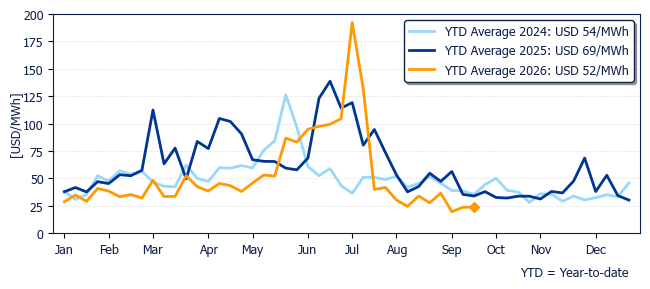
The average price in Polpaico reached USD 23.8/MWh. This was 1% higher than last week and 30% lower compared to one year ago.
|
|
Marginal cost evolution in Polpaico during past years
|
|
|
|
|
|
|
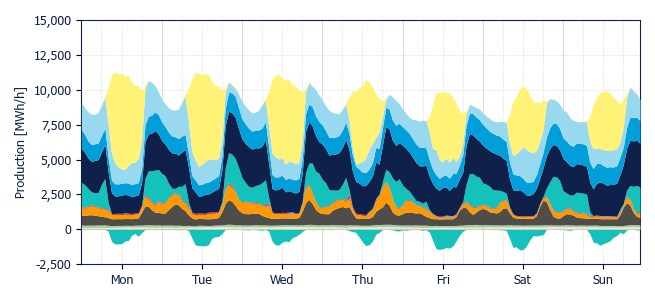
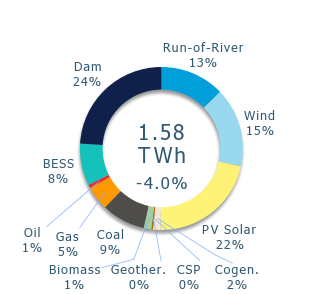
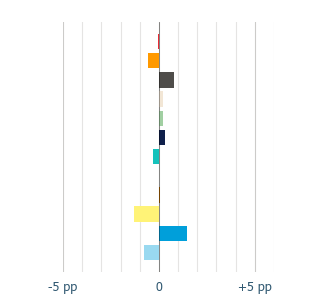
The generation mix presented small changes compared to last week. Run-of-river increase its share by 1.4 pp, while dam increased by just 0.3 pp. Fossil-fueled generation had an increase in coal by 0.8 pp and decreases in gas and oil by 0.6 pp and 0.1 pp, respectively. Regarding renewables, all of them decreased: wind by 0.8 pp, solar by 1.3 pp and BESS by 0.3 pp.
|
|
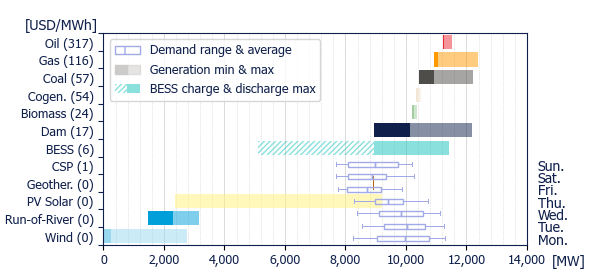
Peak demand in the system reached 11.3 GW at 10 AM of Monday. At the time, wind and solar represented 71.1% of the generation mix.
|
|
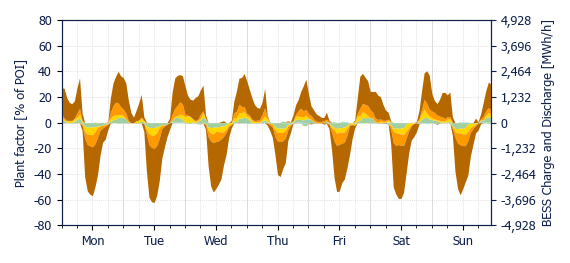
In terms of BESS, their highest participation rate was registered at 10 PM of Saturday, when it accounted for 27.0% of the system’s share and 2.5 GW of output.
|
|
Generation Mix
|
|
|
|
|
Variation
|
|
|
|
|
Power range by energy sources (average prices)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Geothermal
|
|
Cogeneration
|
|
Biomass
|
|
Coal
|
|
|
Gas
|
|
Oil
|
|
BESS
|
|
Dam
|
|
|
Run-of-river
|
|
Wind
|
|
PV Solar
|
|
CSP
|
|
|
|
|
|
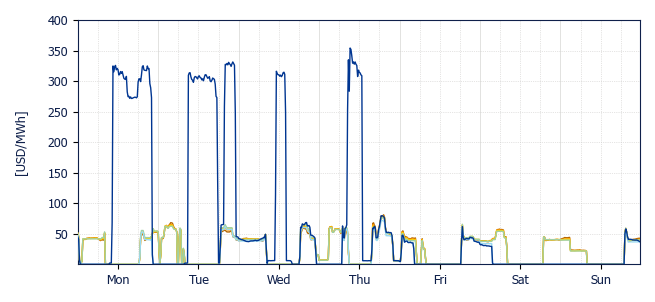
Prices kept a similar behaviour compared to last week, with the usual congestion in the southern areas:
|
- 500kV Charrúa – Ancoa line congested every day of the week at morning and night and even for a few minutes on Thursday mid-day. This caused a price decoupling in the system, with prices in Charrúa, and at times Puerto Montt, falling to USD 0/MWh for several hours, including most of the weekend.
- 220kV Lastarria – Ciruelos line congested from Monday to Thursday, both in solar and non-solar hours. This congestion also price-decoupled Puerto Montt, forcing once again the operation of oil-fired Trapen power plant to meet the demand, setting a peak price of the week of USD 332.7/MWh at 9 AM of Thursday.
- 220kV Charrúa – Santa Clara line congested on Tuesday during solar hours, dropping prices to USD 0/MWh in Santa Clara and Cautín, however, given a congestion in 220kV Cautín-Ciruelos line at the time, Puerto Montt remained with high prices.
|
|
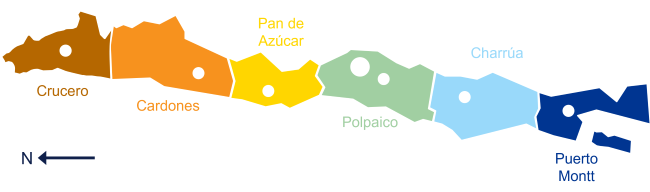
These congestions affected mostly the south-centre and south areas of the SEN, represented by Charrúa and Puerto Montt, respectively. The rest of the reference nodes of the SEN remained coupled.
|
|
In total, the number of USD 0/MWh hours was 64 for the reference nodes Crucero, Cardones, Pan de Azúcar, and Polpaico; 110 for Charrúa; and 77 for Puerto Montt.
|
|
|
|
|
|
|
Crucero
USD 23.7/MWh
|
|
Cardones
USD 23.7/MWh
|
|
Pan de Azúcar
USD 23.8/MWh
|
|
|
|
|
Polpaico
USD 23.8/MWh
|
|
Charrúa
USD 12.8/MWh
|
|
Puerto Montt
USD 69.5/MWh
|
|
|
|
|
|
Solar and Wind production & BESS dispatch
|
|
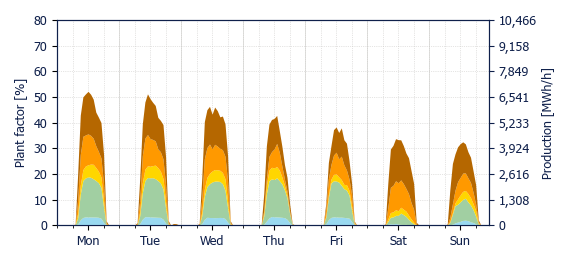
Solar generation decreased 9.4% compared to last week (-35.5 GWh), affected by decreases in all the areas, except from Polpaico where it remained stable. The highest plant factor was seen in Charrúa area with 20.9%, while the lowest was at Pan de Azúcar and Crucero areas with 13.3% and 13.9%, respectively. The system-wide solar plant factor reached 15.5%.
|
|
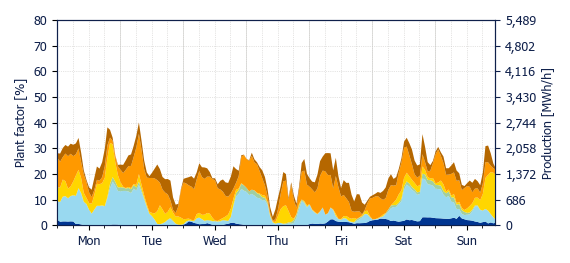
Wind generation decreased 8.5% compared to last week (-23.2 GWh), affected by decreases in Pan de Azúcar and Cardones areas that could not be balanced by the increases in the remaining areas. Even with a lowest output than last week, the Cardones area presented the highest weekly plant factor with 29.4%, while the lowest was at Pan de Azúcar with only 10.0%. The system-wide wind plant factor reached 21.6%.
|
|
Regarding BESS, their output decreased by 7.3% (-10.4 GWh) affected by a big decrease in the Crucero area of 13.5 GWh.
|
|
Curtailment rate was 16.2% for wind (48.8 GWh) and 18.1% for solar (90.2 GWh), representing a combined weekly curtailment rate of 17.0%, which is 3.6 pp higher than last week.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Crucero
USD 2.9/MWh
|
|
Cardones
USD 2.2/MWh
|
|
Pan de Azúcar
USD 2.5/MWh
|
|
|
|
|
Polpaico
USD 3.2/MWh
|
|
Charrúa
USD 3.2/MWh
|
|
Puerto Montt
USD 135.3/MWh
|
|
|
|
|
Energy weighted average spot price using PV production by zone
|
|
|
|
|
|
|
Crucero
USD 22.3/MWh
|
|
Cardones
USD 22.2/MWh
|
|
Pan de Azúcar
USD 24.2/MWh
|
|
|
|
|
Polpaico
USD 29.6/MWh
|
|
Charrúa
USD 9.1/MWh
|
|
Puerto Montt
USD 15.6/MWh
|
|
|
|
|
Energy weighted average spot price using wind production by zone
|
|
|
|
BESS discharge capture price
|
|
|
|
|
Crucero
USD 37.9/MWh
|
|
Cardones
USD 40.8/MWh
|
|
Pan de Azúcar
USD 39.3/MWh
|
|
|
|
|
Polpaico
USD 37.7/MWh
|
|
Charrúa
USD 32.4/MWh
|
|
|
|
|
Energy weighted average spot price using BESS discharge by zone
|
|
|
|
BESS charge capture price
|
|
|
|
|
Crucero
USD 1.1/MWh
|
|
Cardones
USD 0.9/MWh
|
|
Pan de Azúcar
USD 1.1/MWh
|
|
|
|
|
Polpaico
USD 3.8/MWh
|
|
Charrúa
USD 9.1/MWh
|
|
|
|
|
Energy weighted average spot price using BESS charge (both from co-located power plant and from grid) by zone
|
|
|
|
|
|
DNV, Magdalena 181, Las Condes, Santiago, Chile
|
|
|
|
|
|
|