|
|
VOL 13 | NUM 6 | 28 August 2026
|
|
|
|
|
|
|
|
CHILE | 17 - 23 August 2026
|
|
|
|
Power Markets Weekly
is a brief weekly review of the electric market operation in Chile, Mexico, Iberia, France and Italy. If you are not a subscriber, please feel free to subscribe
here
|
|
|
|
|
|
DNV offers tools for Wholesale Market analysis and operation:
- DNV Power Analytics (DNV-PA) is our web-based platform that provides access to constantly updated long-term energy price forecasts.
- With a refined design and an improved user experience we are upgrading our digital services for our customers.
|
|
|
|
|
|
|
This week, BESS reached a new record participation
|
|
|
|
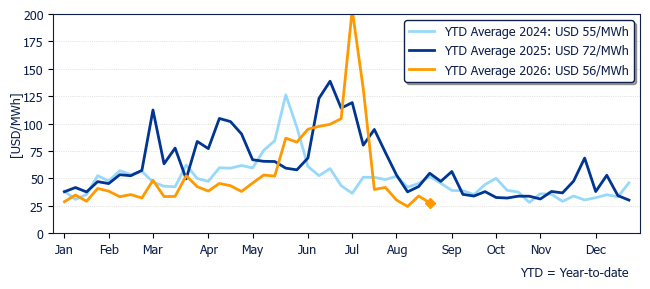
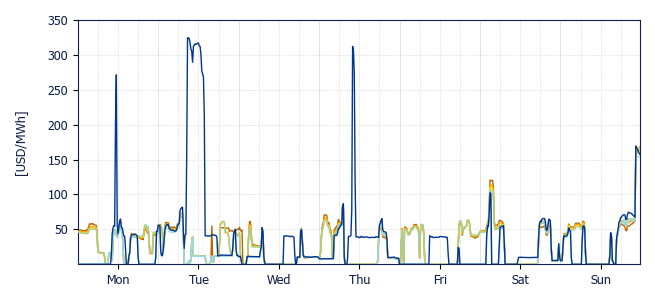
The average price in Polpaico dropped by 18.2% compared to last week, reaching USD 27.7/MWh. Compared to the same week last year, it is 49.3% lower.
|
|
Marginal cost evolution in Polpaico during past years
|
|
|
|
|
|
|
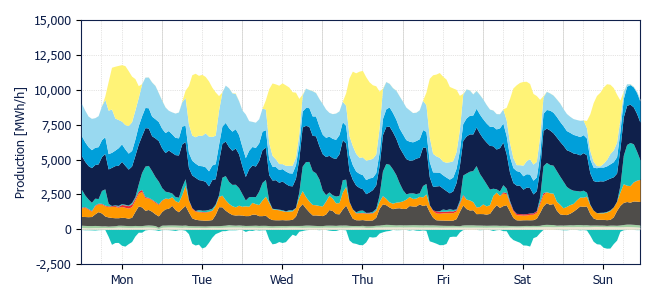
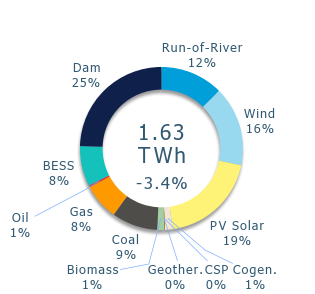
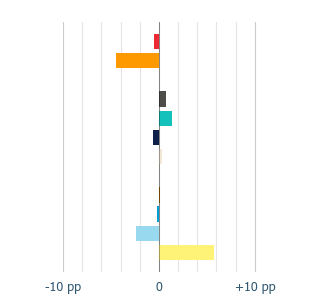
This week, the generation mix had great variations. Gas dropped its share by 4.5 pp, wind by 2.4 pp, dam by 0.7 pp and run-of-river by 0.2 pp. Conversely, solar had a major increase of 5.7 pp, BESS by 1.3 pp and coal by 0.8 pp. Overall, this meant that hydro represented 37.0% of the mix, wind, solar and BESS 43.2% and thermals 16.6%.
|
|
Peak demand reached 11.8 GW on Monday at 12 PM. At the time, solar and wind provided 48.1% of the mix, while thermals represented 12.6%.
|
|
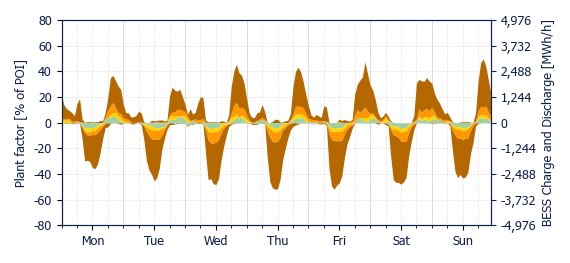
BESS participation had its peak on Friday at 10 PM, when it accounted for 29.6% of the mix, a record share for the technology. BESS also broke its record of injections on Sunday at 8 PM, when they reached 3,092 MW.
|
|
Generation Mix
|
|
|
|
|
Variation
|
|
|
|
|
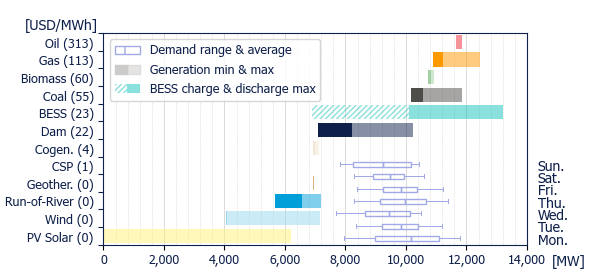
Power range by energy sources (average prices)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Geothermal
|
|
Cogeneration
|
|
Biomass
|
|
Coal
|
|
|
Gas
|
|
Oil
|
|
BESS
|
|
Dam
|
|
|
Run-of-river
|
|
Wind
|
|
PV Solar
|
|
CSP
|
|
|
|
|
|
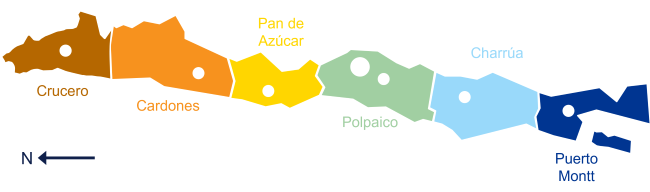
In terms of transmission and price decoupling, main events were as follows:
|
- 500kV Charrúa – Ancoa line congested every day of the week at non-solar hours, decoupling the system from Charrúa to the south.
- 500kV Jadresic – Cumbre line congested in the afternoon and night of Tuesday, momentarily decoupling the Crucero area from the system. This was a preventive move given the electrical storms in the north of Chile. Aside from this line, locally there were different lines that had to stop operations at different times of the day for similar reasons, impacting the injections of renewables and forcing the early operation of coal power plants of the Far North.
- 220kV Lastarria – Ciruelos line congested everyday except from Sunday, decoupling Puerto Montt area, which surpassed USD 300/MWh both on Tuesday and Thursday, presenting its peak price of USD 318/MWh at 9AM of Tuesday.
|
|
Aside from Puerto Montt, the rest of the reference nodes had their peak price on Sunday at 11PM, ranging from USD 153/MWh in Charrúa to SUD 165/MWh in Cardones area.
|
|
Total zero-price hours were 44 in Cardones, Pan de Azúcar, and Polpaico; 43 in Crucero and Puerto Montt; and 68 in Charrúa.
|
|
|
|
|
|
|
Crucero
USD 28.4/MWh
|
|
Cardones
USD 27.7/MWh
|
|
Pan de Azúcar
USD 27.6/MWh
|
|
|
|
|
Polpaico
USD 27.7/MWh
|
|
Charrúa
USD 14.9/MWh
|
|
Puerto Montt
USD 33.1/MWh
|
|
|
|
|
|
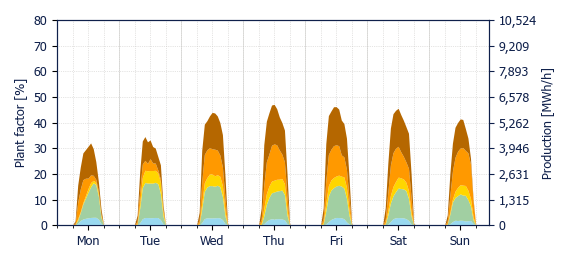
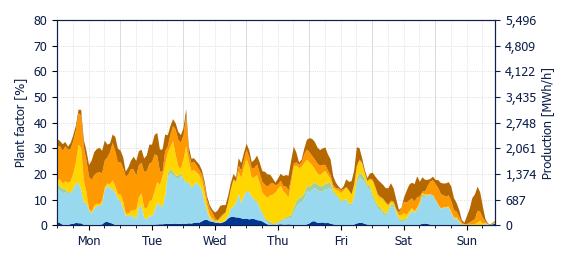
Solar and Wind production & BESS dispatch
|
|
Solar generation grew by 37% this week (+85.5 GWh). The largest increase was recorded in the Polpaico area (+37.5 GWh), while no area registered decreases. The highest average plant factor was observed in Charrúa at 19.5%, while the lowest was in Puerto Montt at 11.4%. The system-wide average plant factor reached 14.3%.
|
|
On the other hand, wind generation dropped by 16% (-48.9 GWh), with a particularly sharp decline of 68.5 GWh in the Cardones area. This decrease was partially offset by an increase of 35.3 GWh in the Charrúa area, which also recorded the highest average plant factor at 30.7%. The lowest plant factor was observed in the Puerto Montt area, at just 12.8%. The system-wide average plant factor reached 22.3%.
|
|
Finally, BESS injections had a 16% increase compared to last week (+17.6 GWh), driven by the 10.8 GWh increase in the Crucero area, 5.7 GWh in the Cardones area and 1.1 GWh in the Pan de Azúcar area.
|
|
This week, curtailment rates reached 9.1% for wind (25.8 GWh) and 10.2% for solar (43.7 GWh), with a weighted average of 9.6%, 3.1 pp higher than last week.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Crucero
USD 5.7/MWh
|
|
Cardones
USD 4.4/MWh
|
|
Pan de Azúcar
USD 4.6/MWh
|
|
|
|
|
Polpaico
USD 6.1/MWh
|
|
Charrúa
USD 6.4/MWh
|
|
Puerto Montt
USD 35.8/MWh
|
|
|
|
|
Energy weighted average spot price using PV production by zone
|
|
|
|
|
|
|
Crucero
USD 28.6/MWh
|
|
Cardones
USD 30.0/MWh
|
|
Pan de Azúcar
USD 23.3/MWh
|
|
|
|
|
Polpaico
USD 31.2/MWh
|
|
Charrúa
USD 11.0/MWh
|
|
Puerto Montt
USD 21.1/MWh
|
|
|
|
|
Energy weighted average spot price using wind production by zone
|
|
|
|
BESS discharge capture price
|
|
|
|
|
Crucero
USD 39.2/MWh
|
|
Cardones
USD 37.8/MWh
|
|
Pan de Azúcar
USD 35.7/MWh
|
|
|
|
|
Polpaico
USD 40.3/MWh
|
|
Charrúa
USD 20.6/MWh
|
|
|
|
|
Energy weighted average spot price using BESS discharge by zone
|
|
|
|
BESS charge capture price
|
|
|
|
|
Crucero
USD 5.9/MWh
|
|
Cardones
USD 4.3/MWh
|
|
Pan de Azúcar
USD 5.4/MWh
|
|
|
|
|
Polpaico
USD 8.4/MWh
|
|
Charrúa
USD 9.1/MWh
|
|
|
|
|
Energy weighted average spot price using BESS charge (both from co-located power plant and from grid) by zone
|
|
|
|
|
|
DNV, Magdalena 181, Las Condes, Santiago, Chile
|
|
|
|
|
|
|