|
|
VOL 13 | NUM 5 | 21 August 2026
|
|
|
|
|
|
|
|
CHILE | 10 - 16 August 2026
|
|
|
|
Power Markets Weekly
is a brief weekly review of the electric market operation in Chile, Mexico, Iberia, France and Italy. If you are not a subscriber, please feel free to subscribe
here
|
|
|
|
|
|
DNV offers tools for Wholesale Market analysis and operation:
- DNV Power Analytics (DNV-PA) is our web-based platform that provides access to constantly updated long-term energy price forecasts.
- With a refined design and an improved user experience we are upgrading our digital services for our customers.
|
|
|
|
|
|
|
Two circuits out, no lights out: Norte Grande suffers brief island operation
|
|
|
|
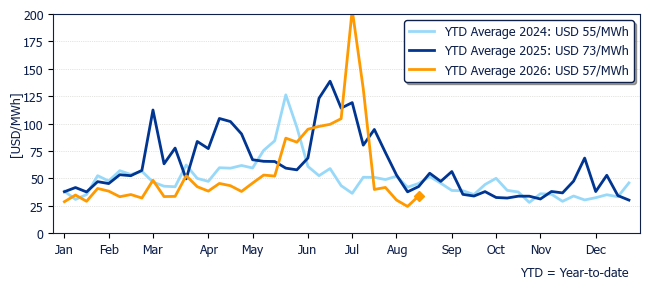
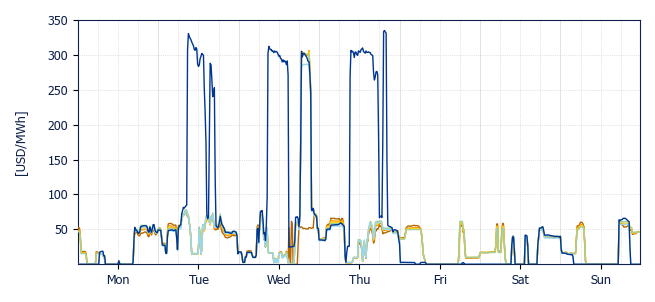
The average price in Polpaico was USD 33.9/MWh, 39.0% higher than last week and 20.3% lower than the same week one year ago.
|
|
Marginal cost evolution in Polpaico during past years
|
|
|
|
|
|
|
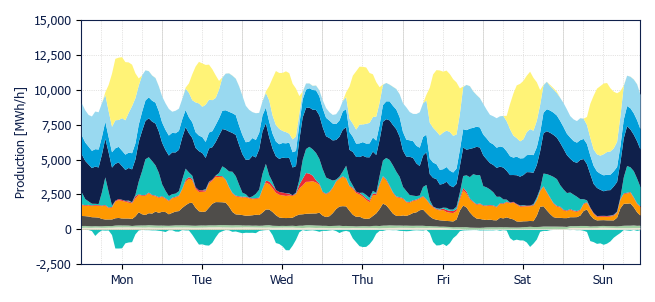
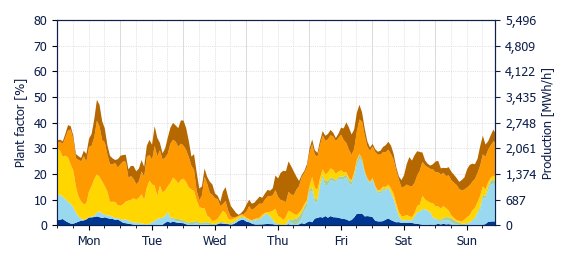
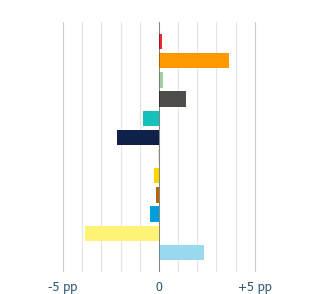
This week, the thermal generation share increased by 5.2 pp, mainly driven by a 3.6 pp rise in gas-fired generation. Oil and coal-fired generation shares also grew by 0.2 pp and 1.4 pp, respectively.
|
|
Hydro share declined compared with last week, dam generation share down by 2.2 pp and run-of-river down by 0.5 pp.
|
|
The solar generation share fell by 3.9 pp this week, whereas the wind generation share rose by 2.3 pp.
|
|
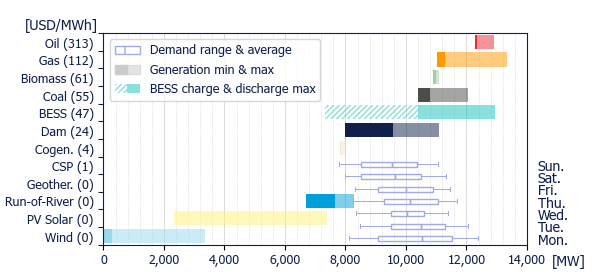
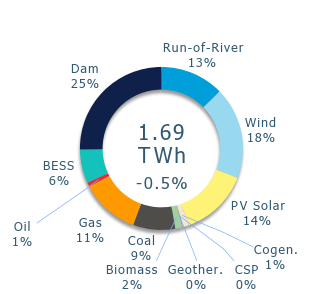
Generation peaked at 12.3 GW on Monday at 1 PM, with solar, wind and CSP accounting for 54.2% of the total output at that hour.
|
|
BESS injection to the system peaked at 8 PM on Monday, representing 22.4% of the total output at that hour.
|
|
Generation Mix
|
|
|
|
|
Variation
|
|
|
|
|
Power range by energy sources (average prices)
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Geothermal
|
|
Cogeneration
|
|
Biomass
|
|
Coal
|
|
|
Gas
|
|
Oil
|
|
BESS
|
|
Dam
|
|
|
Run-of-river
|
|
Wind
|
|
PV Solar
|
|
CSP
|
|
|
|
|
|
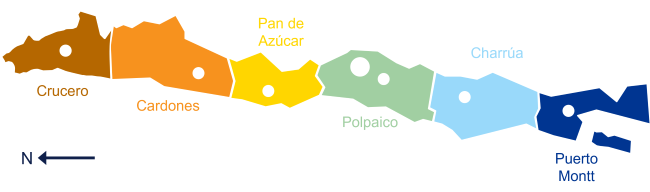
This week, marginal costs peaked at USD 330.6/MWh in Puerto Montt on Tuesday at 9 AM, set by the oil-fired plant Trapén. During this high-price period, Puerto Montt was decoupled from the rest of the system due to congestion on the 220 kV Lastarria - Ciruelos line. This congestion also was present on Wednesday, Thursday and Saturday. On Friday, the south zone was also decoupled from the rest of the system, but this time due to congestion on the 220 kV Charrúa - Santa Clara line. This was driven by high wind generation in the central-south part of the grid, resulting in zero marginal costs from Santa Clara southwards.
|
|
On Wednesday, both circuits of the 500 kV Cumbre - Jadresic line tripped, temporarily islanding the Norte Grande from the rest of the SEN. The system was resynchronised shortly afterwards.
|
|
The 500 kV Charrúa - Ancoa corridor also experienced congestion early on Monday, from Friday evening into Saturday, and again on Sunday.
|
|
|
|
|
|
|
Crucero
USD 28.4/MWh
|
|
Cardones
USD 33.2/MWh
|
|
Pan de Azúcar
USD 33.4/MWh
|
|
|
|
|
Polpaico
USD 33.9/MWh
|
|
Charrúa
USD 26.6/MWh
|
|
Puerto Montt
USD 65.6/MWh
|
|
|
|
|
|
Solar and Wind production & BESS dispatch
|
|
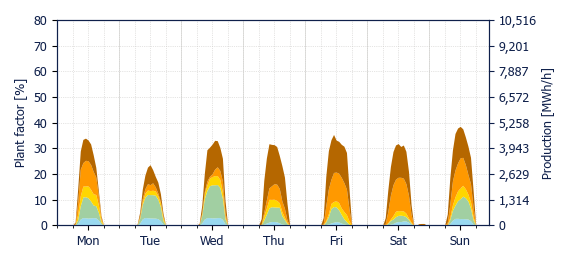
Solar output decreased by 22.3% | 66.7 GWh compared to last week. Regarding the plant factor, the highest was 12.2% in Cardones, while the lowest was 9.0% in Polpaico. The system-wide solar plant factor was 10.5%.
|
|
Wind generation increased this week by 14.1% | 37.8 GWh relative to last week. The highest plant factor was 41.5% in Cardones, while the lowest was 18.2% in Polpaico. The system-wide wind plant factor was 26.6%.
|
|
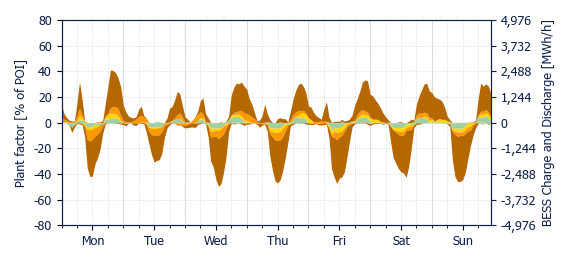
BESS showed a decrease in injection of 11.3% | 14.5 GWh, and a fall in charges by 16.2% | 23.9 GWh, relative to last week. Based on the hourly BESS dispatch profile, injections continue to occur predominantly before midnight, resulting in a significant reduction in BESS injections during the early morning hours.
|
|
This week, curtailment rates reached 6.8% | 22.6 GWh for wind and 6.3% | 18.9 GWh for solar. This resulted in a combined system-wide curtailment rate of 6.5%, which represents a decrease of 40.1 pp relative to last week. Curtailment was concentrated on Sunday, when low demand and abundant renewable output resulted in system-wide zero marginal costs during much of the solar period.
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Crucero
USD 10.8/MWh
|
|
Cardones
USD 6.9/MWh
|
|
Pan de Azúcar
USD 10.1/MWh
|
|
|
|
|
Polpaico
USD 15.3/MWh
|
|
Charrúa
USD 13.7/MWh
|
|
Puerto Montt
USD 129.6/MWh
|
|
|
|
|
Energy weighted average spot price using PV production by zone
|
|
|
|
|
|
|
Crucero
USD 27.3/MWh
|
|
Cardones
USD 26.8/MWh
|
|
Pan de Azúcar
USD 29.7/MWh
|
|
|
|
|
Polpaico
USD 34.2/MWh
|
|
Charrúa
USD 10.6/MWh
|
|
Puerto Montt
USD 28.4/MWh
|
|
|
|
|
Energy weighted average spot price using wind production by zone
|
|
|
|
BESS discharge capture price
|
|
|
|
|
Crucero
USD 37.1/MWh
|
|
Cardones
USD 48.3/MWh
|
|
Pan de Azúcar
USD 49.2/MWh
|
|
|
|
|
Polpaico
USD 61.2/MWh
|
|
Charrúa
USD 110.5/MWh
|
|
|
|
|
Energy weighted average spot price using BESS discharge by zone
|
|
|
|
BESS charge capture price
|
|
|
|
|
Crucero
USD 12.0/MWh
|
|
Cardones
USD 13.7/MWh
|
|
Pan de Azúcar
USD 8.5/MWh
|
|
|
|
|
Polpaico
USD 15.6/MWh
|
|
Charrúa
USD 13.2/MWh
|
|
|
|
|
Energy weighted average spot price using BESS charge (both from co-located power plant and from grid) by zone
|
|
|
|
|
|
DNV, Magdalena 181, Las Condes, Santiago, Chile
|
|
|
|
|
|
|